MAY 2023
Seed Round Closes
15+ investors commit over US$4 million to build STIX.
Every fraud begins the same way: with trust.
“I would honestly rather go broke than steal. Never try to scam someone. You will never be able to look yourself in the eye again and karma will destroy you in the future.”
TARANVEER SINGH SABHARWAL (AKA TARAN), PUBLIC POST, MONTHS AFTER HE STOPPED ANSWERING HIS OWN INVESTORS’ CALLS — 1
That's the same man fifteen-plus investors trusted with more than US$4 million.2
Between 2023 and 2025, investors funded STIX, an OTC marketplace for illiquid crypto tokens.3 What they were never told was that, alongside STIX, Taran was building a separate investment fund that bought and sold the same assets STIX brokered for clients—effectively trading as principal against the same market.4
Internally, he acknowledged the conflict more than a year earlier. Rather than shutting it down, he decided to continue.5
Investor reporting deteriorated. Financial statements never arrived. Meaningful updates stopped. At the same time, Taran asked, in writing, for his real financial numbers to be kept out of investor reporting. Not omitted by mistake. Requested.6 The fund itself was backed by investors he never identified, using capital whose origin he never disclosed.6
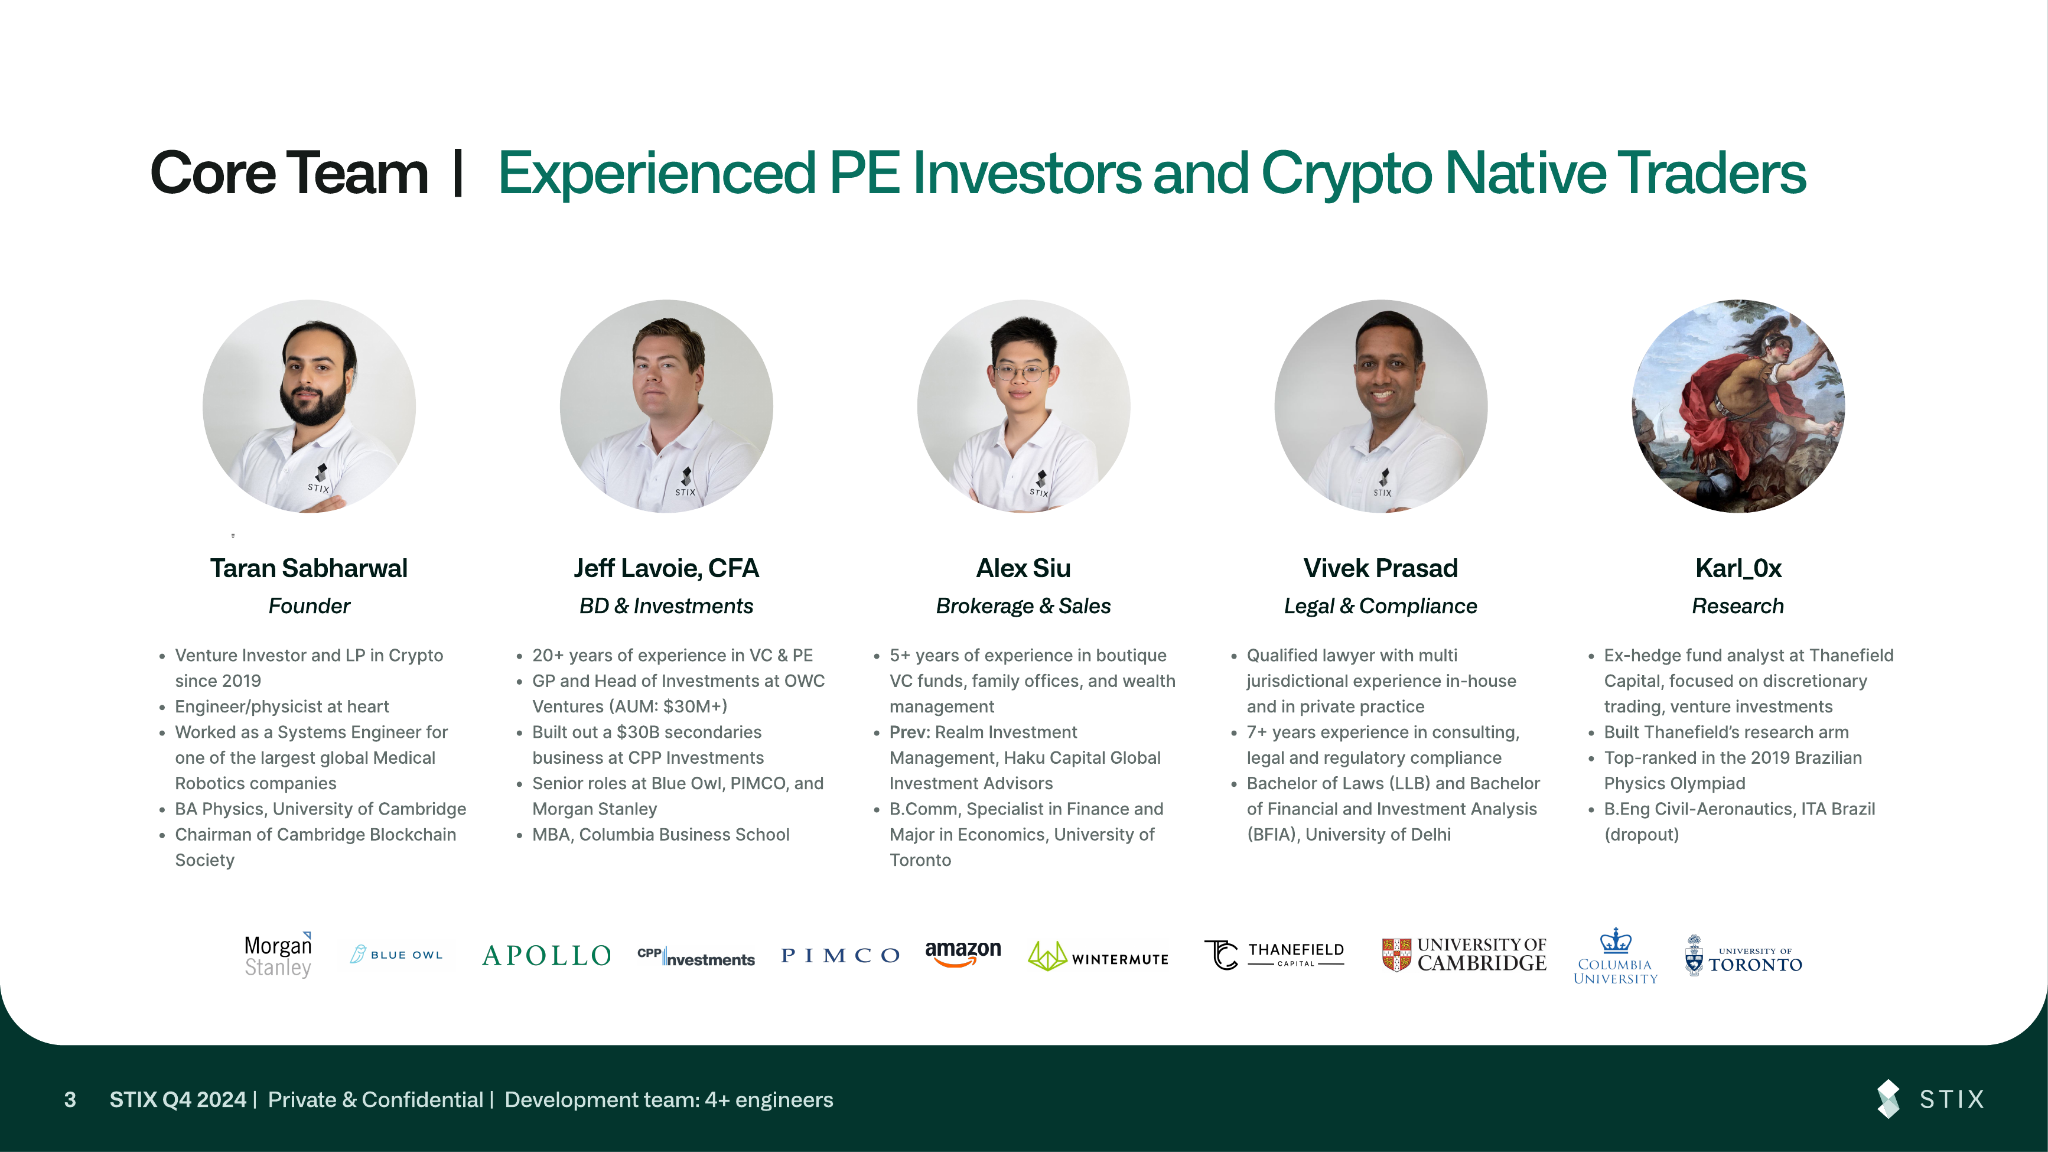
The company wasn't understaffed. Taran told Investor 1 that his own employees—Alex Siu, Jeff Lavoie and Vivek Prasad—“literally run the business without me.”7 Whatever prevented investors from receiving straight answers, it wasn't that nobody was home.
It wasn't one investor being ignored. Communication stopped with all of them. Emails went unanswered. Calls were missed. The entire management team fell silent.8 Investor 1 eventually warned: “You'll hear from all of us acting as a group soon.”9 This website is that group speaking. When Taran resurfaced over a year later, it wasn't with answers. It was to ask how the family was doing.10
The updates never came. The promised conversion never happened.11
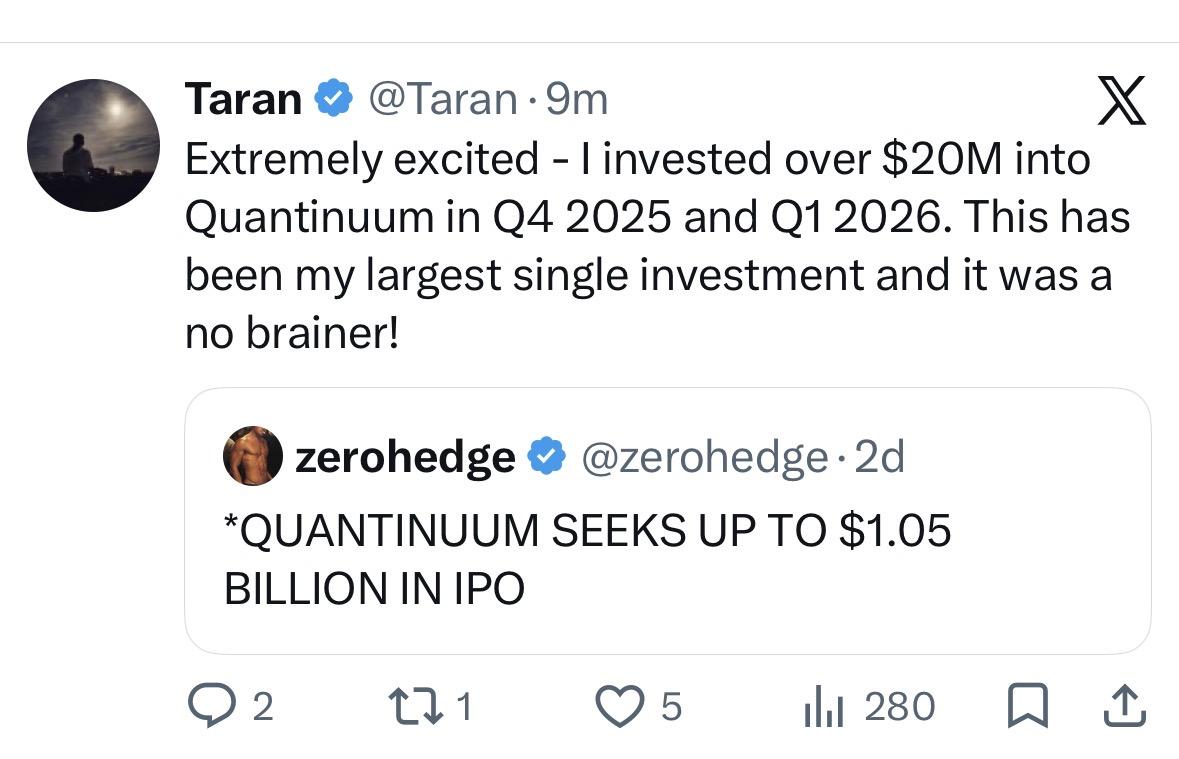
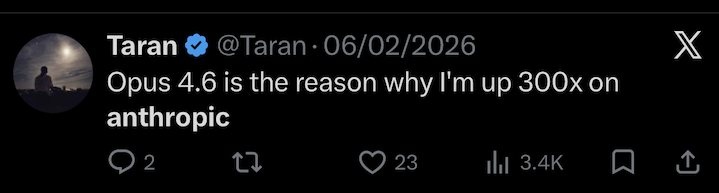
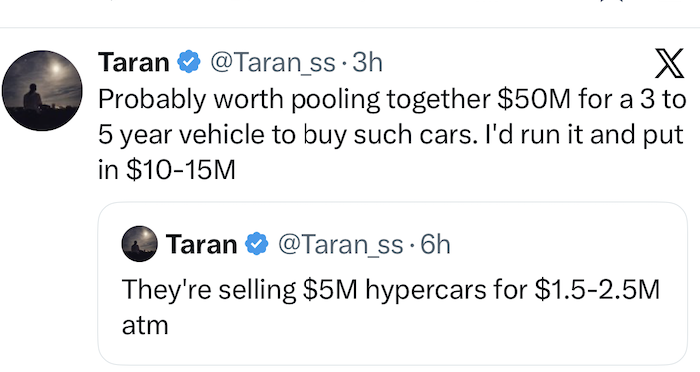
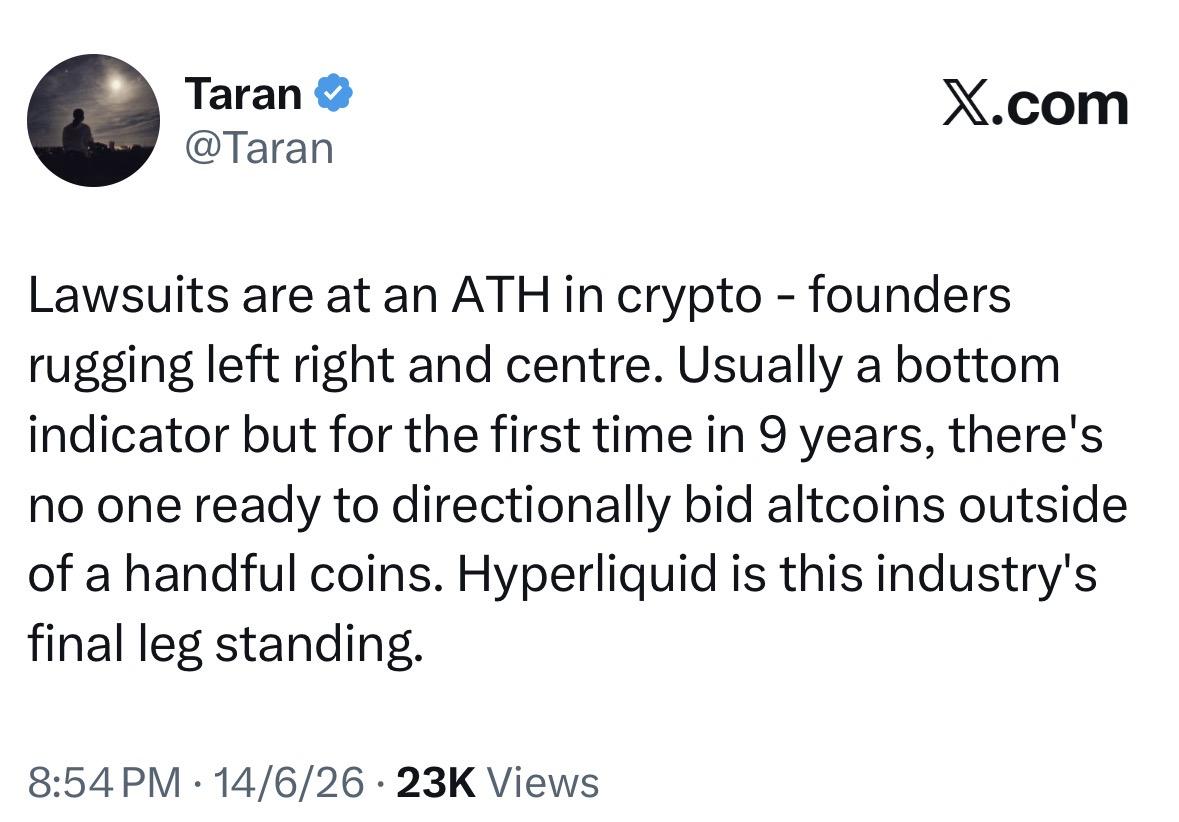
While investors waited for answers, Taran publicly discussed a US$20 million investment into a quantum computing company,12 claimed a 300× return on Anthropic,13 promoted a hypercar investment fund,14 and warned others about founders “rugging left right and centre.”1 He had plenty to say publicly—just nothing to say to the people who had financed STIX.
Between 2023 and 2025, STIX continued raising capital through successive financing rounds at progressively higher valuations—US$18 million, then US$35 million, and finally US$100 million.11 Investors were repeatedly told their SAFEs would convert once the Series A closed. Instead, another SAFE was issued at the same US$100 million valuation cap, while the earlier SAFEs remained outstanding. Years later, investors still held no shares and had received no substantive explanation for why the promised conversion never occurred.11
Viewed in isolation, each event might be explained away. Together, they form a single pattern: investors funded one business while something materially different was built alongside it. Communication stopped when questions became unavoidable. The SAFEs never converted. The explanations never came.15
What that money ultimately funded looks less like an OTC brokerage than a personal investment operation built alongside it.15
This wasn't a startup that quietly failed. It was concealment, self-dealing, and sustained silence over nearly two years.
Call it what it is: fraud.
Taranveer Singh Sabharwal, known as Taran16, is a Cambridge physics graduate, and committee member of the Cambridge Blockchain Society17. He identified a specific problem in the crypto market: trading in locked or illiquid tokens was fragmented, conducted through informal back-channel deals, with no standard pricing or process. His stated solution was STIX18 — a professional over-the-counter marketplace for these transactions.
The concept addressed a genuine market need at the time. As token vesting schedules became longer and larger amounts of capital remained locked, founders, employees, venture investors and funds increasingly sought liquidity before tokens became freely transferable.19 Secondary transactions were becoming an established part of the digital asset ecosystem, yet they remained largely relationship-driven and opaque.20 A professional marketplace for these transactions was, on its face, a credible and commercially attractive proposition.21
Before the BVI company, Taran was sole director and 75%+ owner of SST DIGITAL LTD (formerly SOCRATIX LTD), UK 13899775. Incorporated 8 February 2022. Renamed from SOCRATIX LTD on 15 April 2023 — four days before Socratix Holdings Limited was registered in the BVI (19 April 2023). It was not voluntarily closed. Companies House first gazetted it for compulsory strike-off on 28 January 2025, suspended that action on 14 March 2025, then dissolved it on 22 April 2025. It is his only UK directorship.67
STIX is the commercial brand. The SAFE counterparty is Socratix Holdings Limited (BVI Co. 2122340), registered 19 April 2023.22 The live STIX website attributes the brand to Secondary Global Inc, “an entity incorporated in Panama.”24 Investment contracts define "the Business" narrowly: the conducting of secondary-market over-the-counter cryptocurrency and virtual-asset transactions.23
STIX GLOBAL sp. z o.o. (KRS 0001036546) is an active Polish company, registered 18 May 2023, Warsaw. Public KRS records name Taranveer Singh Sabharwal as president and Socratix Holdings Limited as 100% shareholder. It appeared on Poland’s old virtual-currency register (RDWW-776). That listing is not an EU MiCA licence and does not authorise crypto activity. Poland currently has no firms on the EU CASP register.68
Taran founded and led the company throughout the period covered by this website. He is referred to as Taran throughout; Socratix and STIX are used interchangeably to refer to the company, consistent with how the company refers to itself in its own materials.24
STIX presented itself, throughout the period covered by this website, as a staffed operating company rather than a solo venture. Its public team page and LinkedIn materials identified named personnel across institutional sales, compliance, operations, engineering, and product - including Alex Siu25, Jeff Lavoie, CFA26, Vivek Prasad27, Will Clemente28 and Soeleen Kaur29. In October 2024, Taran told Investor 1 directly that the business no longer depended on him personally: "Alex, Jeff and Vivek literally run the business without me," adding that key-man risk was "mostly gone."
This detail becomes relevant later. Once investor communications stopped, the company was not, on this record, short-staffed or without active personnel — a fact that bears on how any subsequent silence toward investors should be read.
MAY 2023
15+ investors commit over US$4 million to build STIX.
JULY 2023
Missed calls, cancelled meetings and the first investor concerns emerge.
JANUARY 2024
A new SAFE is issued at almost double the previous valuation.
JANUARY 2024
STIX distributes its final investor report. No further meaningful reporting follows.
MARCH 2025
Investors are told the Series A has closed while earlier SAFEs remain outstanding.
2025–2026
Repeated requests for meetings, financial information and updates go unanswered.
2026
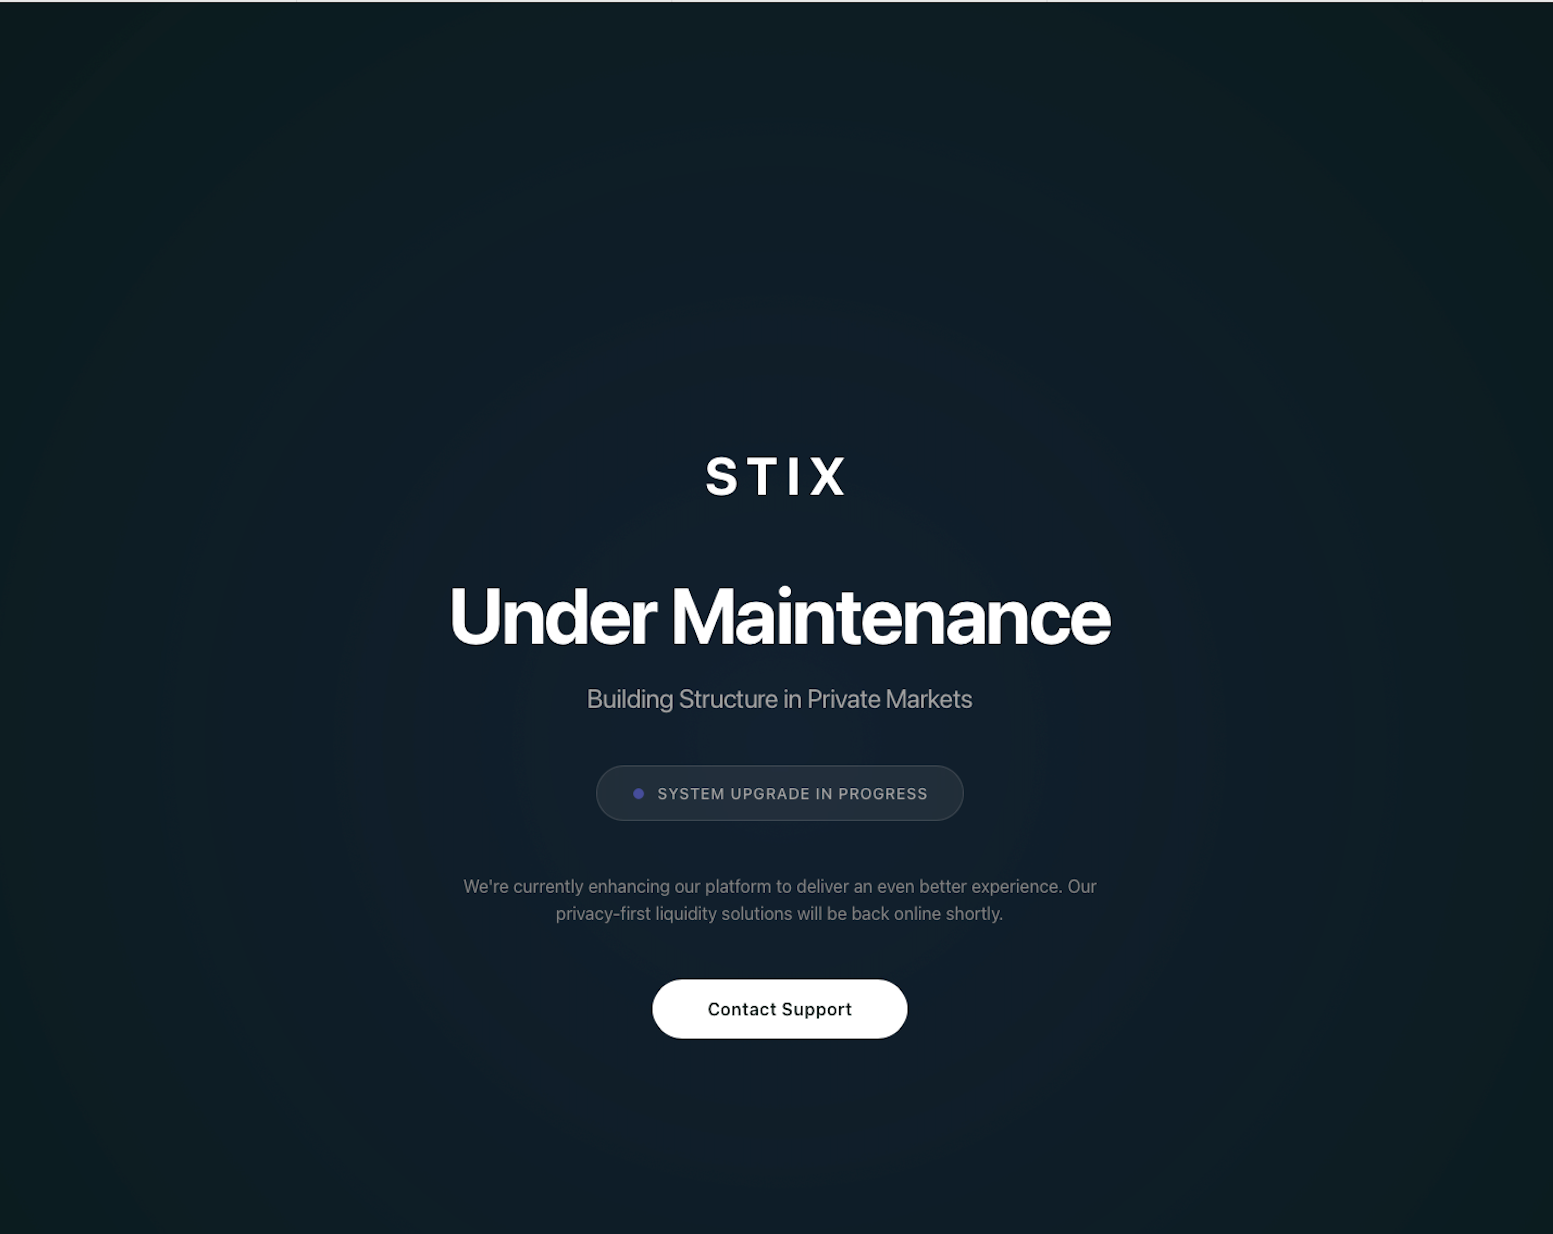
The platform is replaced by an “Under Maintenance” page without explanation.
Q2 2023: $2.7M seed round. Big Brain, Eterna Capital, Fisher8, TLF, Humla Ventures come in alongside.30 At least eight investors invested in Socratix Holdings Limited through SAFE agreements during the seed round.31 Investor 1 invested US$500,000 through a SAFE at a US$18 million post-money valuation cap. Days later, Investor 2 invested US$100,000 on the same terms. The Investor 1 SAFE included on this website is a representative executed agreement from the seed financing. All of the SAFEs provided for automatic conversion only if the company later completed a priced financing raising at least US$5 million.11
Investor 1 signed the SAFE on 2 May 2023. The same day, Taran signed a side letter containing additional commitments regarding future activities and conflicts of interest.32
THE PROMISE
Before taking the money, Taran signed a personal side letter with the lead investor. 2 May 2023. In it, he personally undertook: "not to carry on the Business unless such Business is conducted through the Company or a 100% direct or indirect subsidiary entity of the Company." The Business was defined as "the business of conducting secondary market over-the-counter cryptocurrency and virtual asset transactions." Not a company promise. His name. His signature.32
By August 2023, the team was real and growing. Jeff Lavoie joined as Head of BD — "psyched to have him on, really well connected in the US." 33Days later, asked for a quarterly update, Taran reported a team of eight: CEO, Head of Legal & Compliance, Head of Business Development, Senior Associate, Senior Product Engineer, Senior Frontend Engineer, Frontend Engineer, DevOps Engineer.34 A real company, with a real org chart. That's part of what made the later silence so hard to square — this wasn't a one-man shop that could plausibly go quiet because the founder got overwhelmed.
Throughout 2024, numbers were reported as growing. Investors were kept updated. No formal financials were ever shared. The last investor report they'd ever receive was the Q4 2023 report, published 29 January 2024. 35No financial statements. No revenue figures. No balance sheet. Market commentary, dressed up as an update. Nobody was asking hard questions yet.
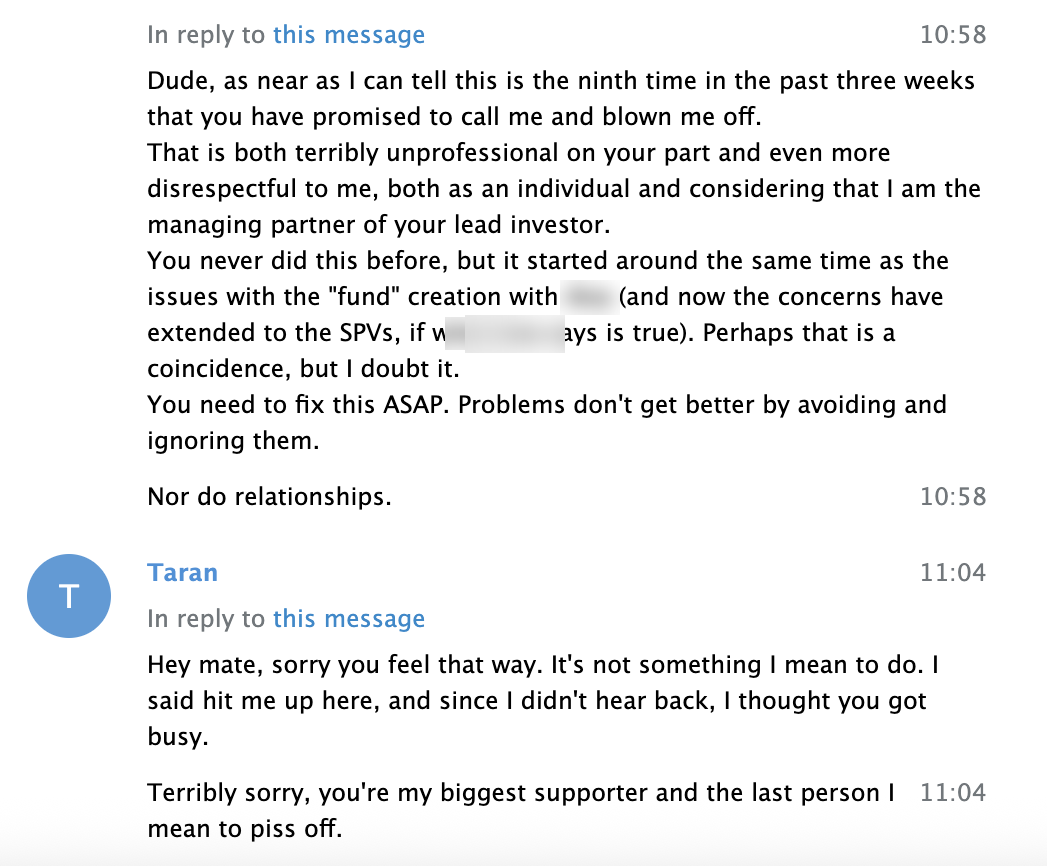
Except someone already was. Three months after the seed closed — 27 July 2023 —Investor 1 confronted Taran directly: "this is the ninth time in the past three weeks that you have promised to call me and blown me off. That is both terribly unprofessional on your part and even more disrespectful to me, both as an individual and considering that I am the managing partner of your lead investor."36
August 2023
Investor 1 traced his concerns to discussions surrounding the proposed investment fund and information from another source, noting that the concerns later extended to possible SPV-related issues.37
Side vehicles. Undisclosed SPVs. The whole pattern this page documents — visible within ninety days of the money landing.
On 17 January 2024, another SAFE was executed at a US$35 million valuation cap.38 More than 90% higher than the cap the first two investors got, eight months earlier, for the identical instrument and identical conversion terms.39
$200,000 · $35M valuation cap
Throughout 2024, Taran remained in regular contact with investors.40 Updates were reported as positive, and STIX maintained an active public presence41 — press appearances, podcast interviews42, and frequent posts on Twitter. No formal financial statements were shared during this period, but investors had, on this record, no immediate cause to press the point.
In the fourth quarter of 2024, Taran circulated a Series A deck to investors — the last formal document they would receive.43It disclosed, for the first time, a planned STIX Asset Management arm: a structure exceeding $50 million in AUM, with deal-specific SPVs, a multi-strategy fund, and a proprietary trading desk, operating under the same brand as the OTC platform investors had funded.
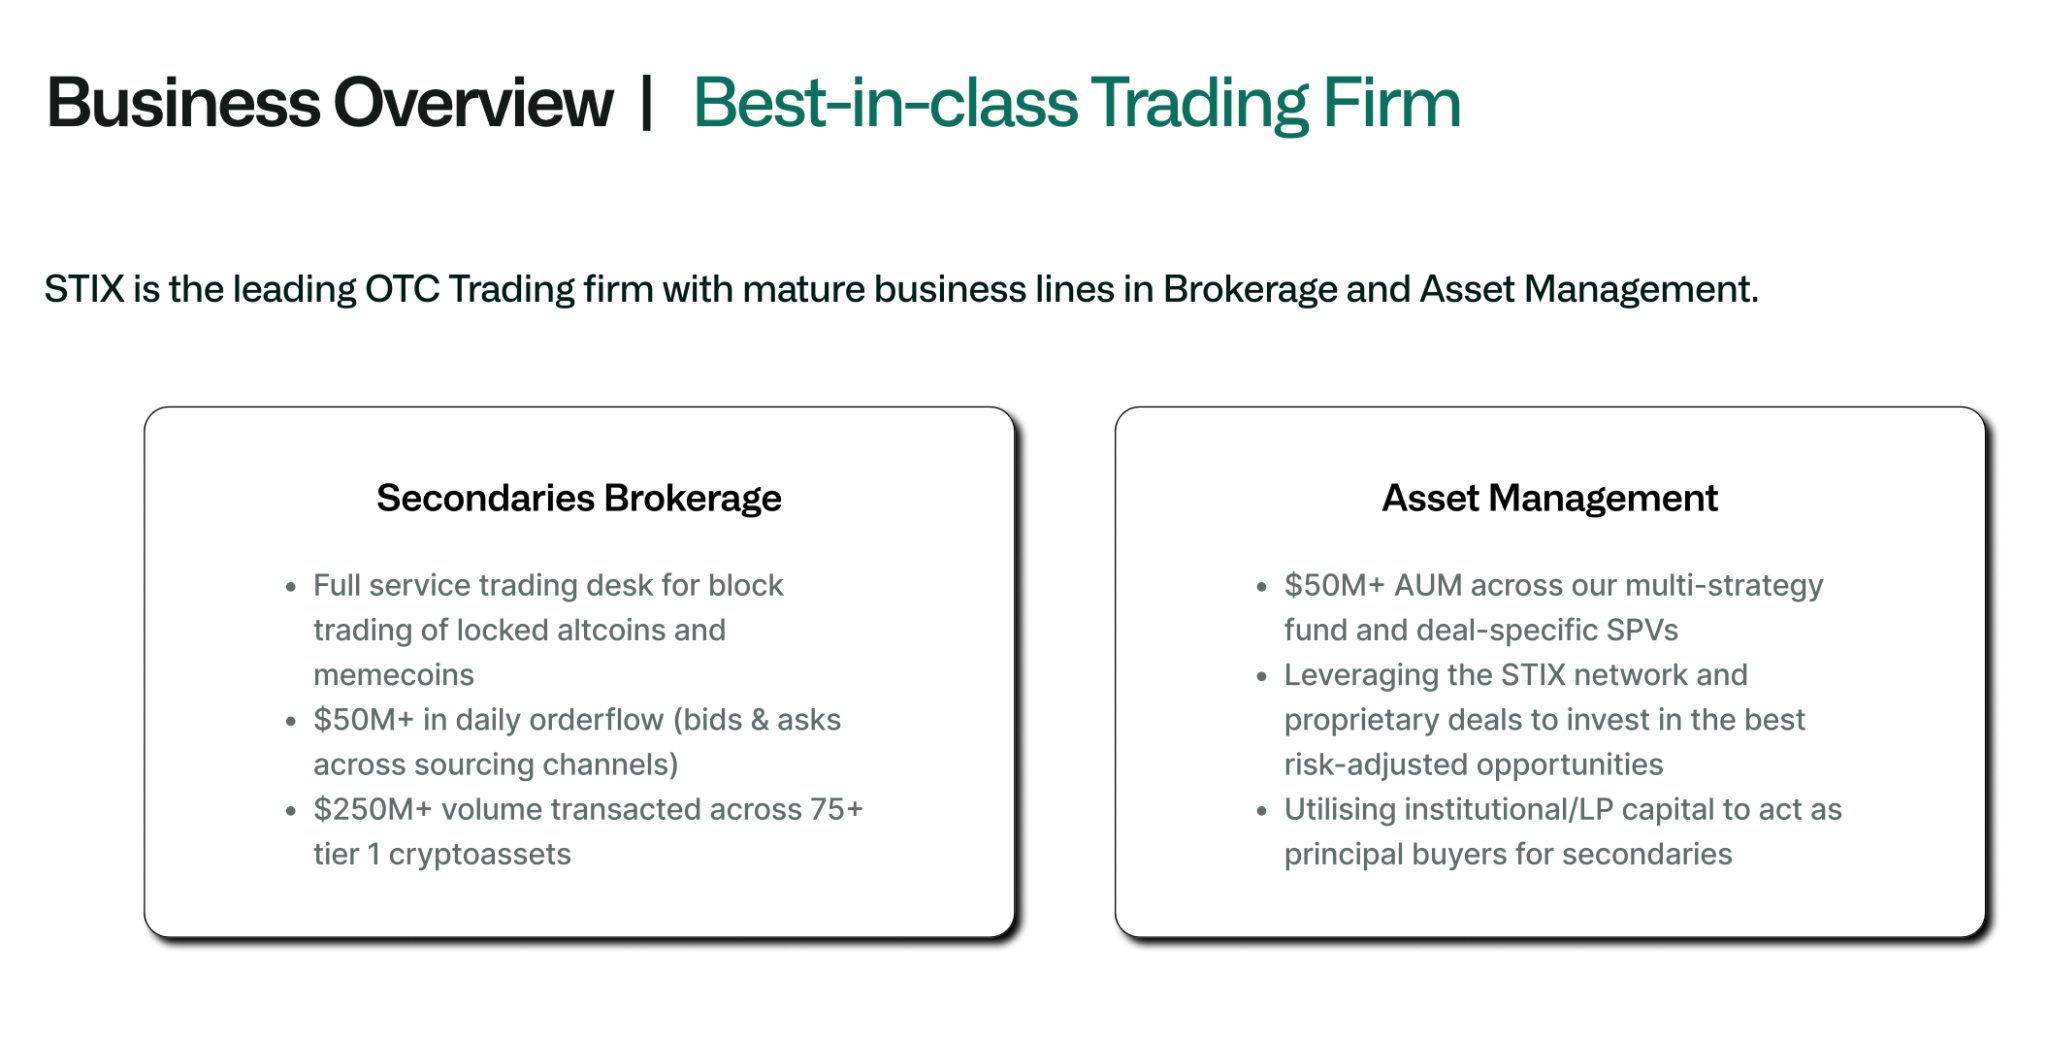
Investor 1 raised the conflict directly at this time — running an investment fund alongside a client-facing brokerage, under one name, using the same relationships and deal flow. Taran acknowledged the concern. The plan proceeded regardless.44
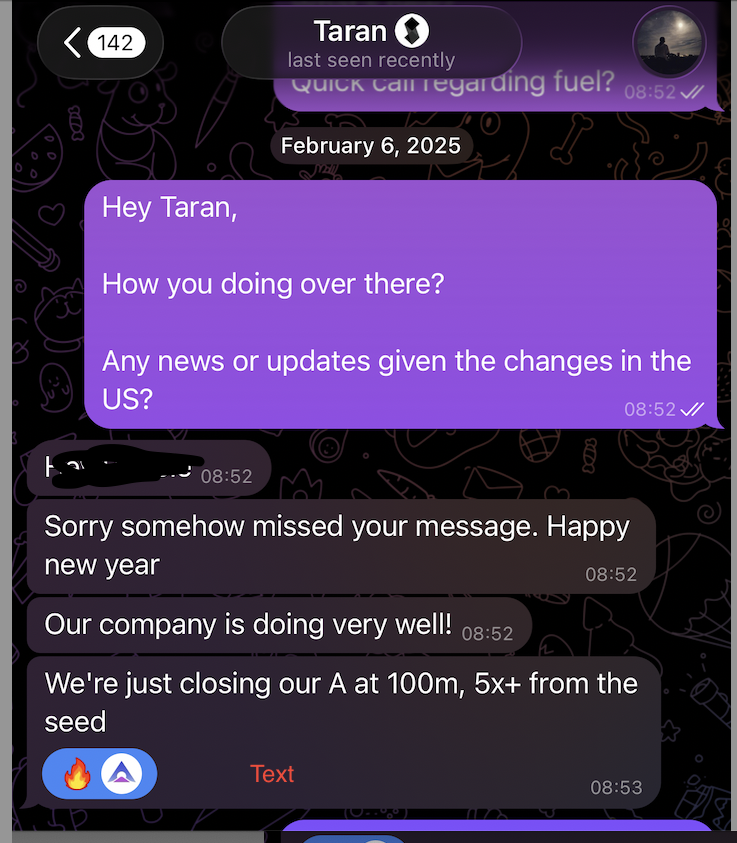
On 6 February 2025, Taran told Investor 2: "Our company is doing very well! We're just closing our A at 100m, 5x+ from the seed."45 What closed on 15 March 2025 was, on its face, a further SAFE instrument — not a certificate of issued shares. Whether that financing met the contractual definition of an Equity Financing cannot be resolved from the document alone.46
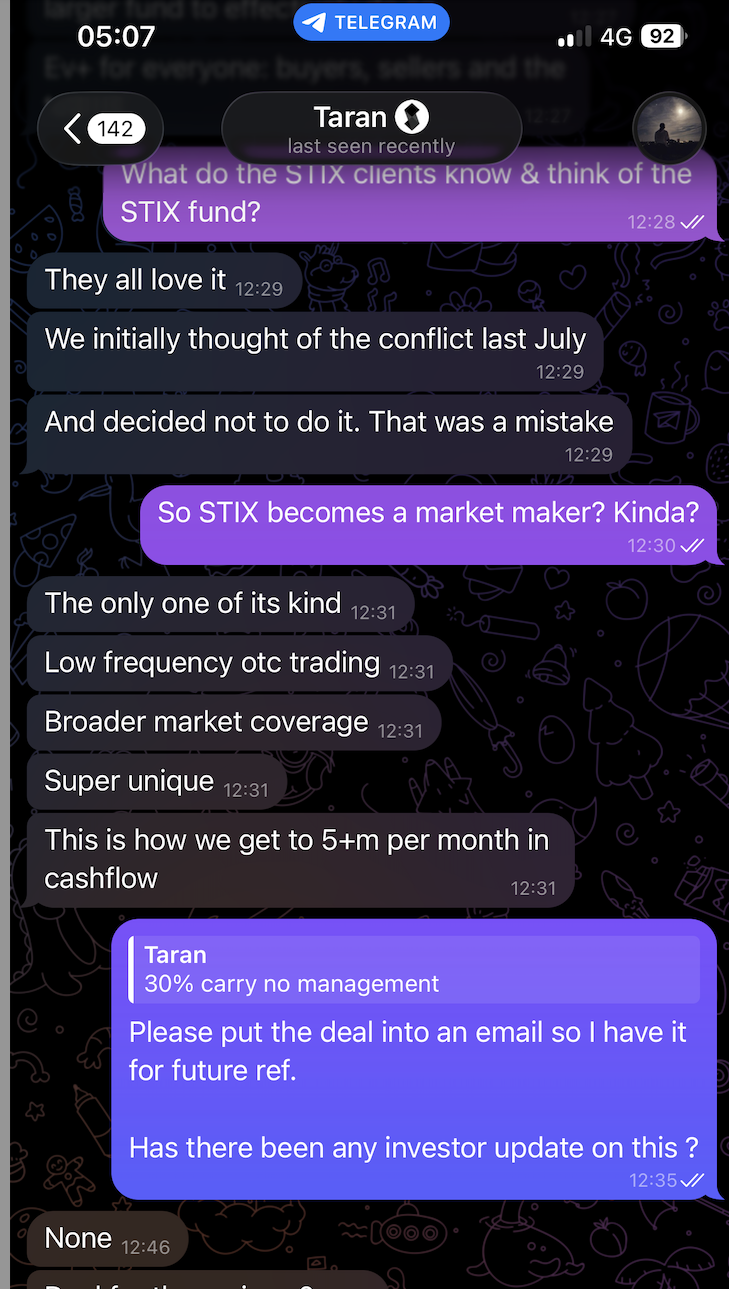
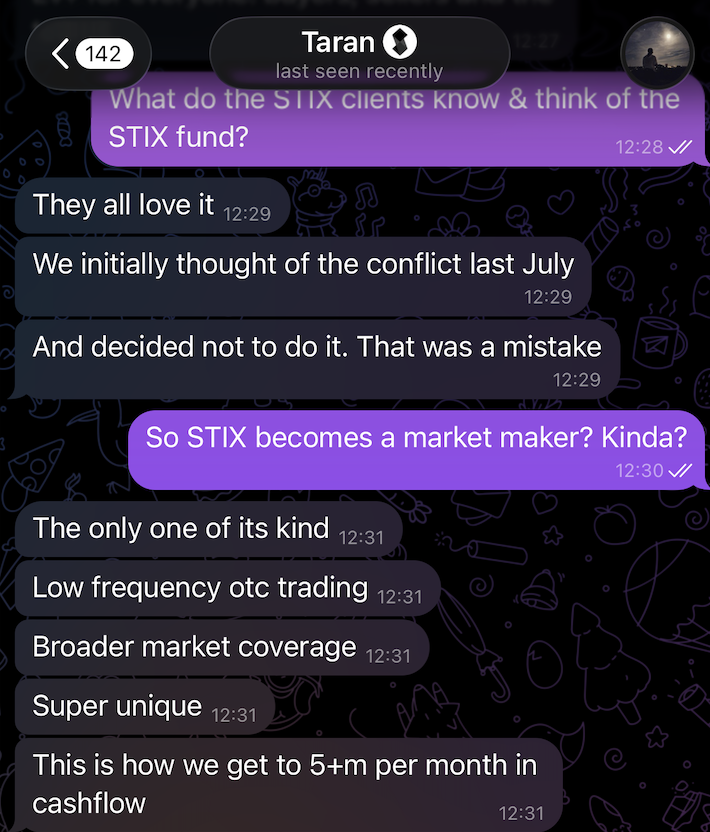
By late 2024, the fund described in the Series A deck was already operating. In private Telegram messages exchanged with Investor 2 on 25 October 2024, Taran said it had raised approximately $4 million toward a $5 million target, with 30 percent carry and no management fee.47Asked how STIX clients viewed the fund, he said "they all love it." Asked whether STIX's own clients were aware of the fund, he replied: "None."
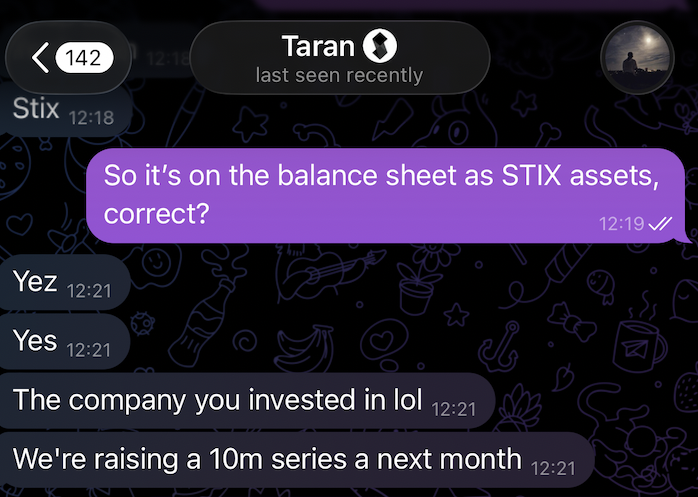
He described the fund's purpose directly: "an experimental vehicle to operate as a principal buyer of secondaries," with a projected cashflow of "5+m per month." 48He disclosed, informally, that STIX had generated $1.3 million in transaction fee revenue and $500,000 in OTC trading revenue — figures that had not appeared in any report to investors.49 Asked whether the fund's assets sat on STIX's own balance sheet, he replied:50
"Yes. The company you invested in lol."
TARAN, TELEGRAM, REPLYING TO INVESTOR 2, WHO ASKED WHETHER FUND ASSETS SAT ON THE COMPANY'S OWN BALANCE SHEET — 25 OCTOBER 202450EXHIBIT 10 · · VIEW ORIGINAL TELEGRAM
In a Telegram conversation with Investor 2 on 25 October 2024, Taran acknowledged that he had recognized the conflict of interest more than a year earlier, stating: "We initially thought of the conflict last July. And decided not to do it. That was a mistake."51
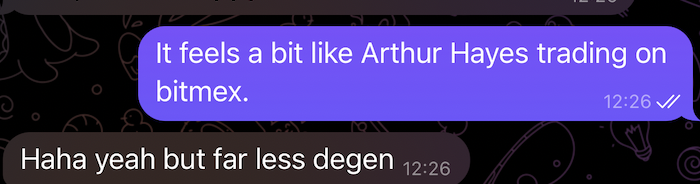
Asked by Investor 2 whether operating a fund alongside a client-facing brokerage would "get weird at any point," Taran replied that it would not: "Sellers love that we're also now buyers."52 He went on to explain that the fund traded as principal against the same order flow STIX brokered for clients: "If we predict someone's gonna buy something at 1.3x in 3 months and it's available rn for 0.8x, we are happy with the duration risk."53 When Investor 2 compared the arrangement to Arthur Hayes's conduct at BitMEX, Taran replied:
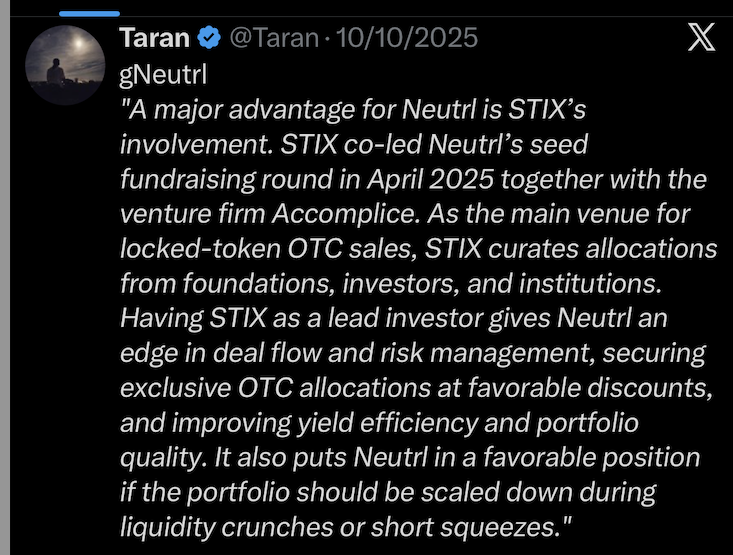
STIX and Accomplice led Neutrl’s US$5 million seed in April 2025.55 Neutrl’s own risk disclosure names CAVERNA AUCTUS INC. as the sole issuer of NUSD.72 In August 2026 Neutrl paused NUSD minting and redemptions over an undisclosed reserve issue.73 Later reporting put liquid assets at about $27 million against a previously cited ~$137 million collateral book.74 A ~$3.5 million Curve LP withdrawal by a team wallet minutes before the freeze has been alleged; it is not proven.75 Pause coverage generally does not name Taran. STIX appears as the 2025 seed lead. A pre-pause risk note described Neutrl as having concentrated counterparty exposure to STIX as the OTC venue for discounted venture-locked tokens.76 STIX investors were not informed that fund capital was being deployed into these investments, nor were they provided with updates regarding the fund's activities.
Neutrl’s founder, Behrin Naidoo, previously co-founded Fyde Treasury. Fyde’s December 2023 $3.2 million seed was led by OP Crypto Ventures (later Inception Capital), where Sabharwal had been Head of DeFi Research. Naidoo publicly said Fyde co-hosted an EthCC Paris 2023 event with STIX and OP Crypto; Sabharwal commented on that post. A third-party directory lists him as a Fyde advisor. Big Brain Holdings appears on both Fyde’s seed and STIX’s $2.7 million seed. Fyde’s TRSY vault is still listed on DefiLlama at low six-figure TVL. No source opened for this page describes Fyde as a rug, hack, or official unwind.77
2025
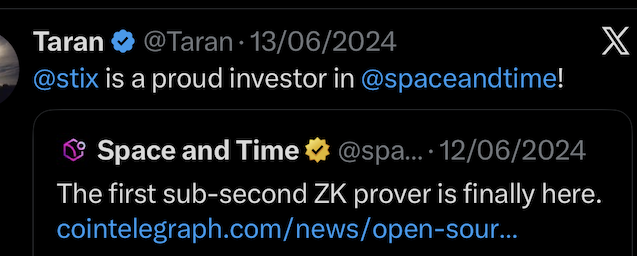
The fund also recorded investments in Ethena Labs56, Spectral Labs, Space and Time, Capx AI, and the Shiba Inu ecosystem via Treats for Shib.57 These deployments appear to have occurred through a vehicle outside Socratix Holdings Limited, with no disclosure to the investors who had funded the parent company — a fact that bears directly on the side letter discussed earlier.
June 2024
A STIX team member separately described Neutrl, a recipient of the fund's capital, as "a growing client of STIX's on the buy side" in a public thread, while disclosing his own personal position in the same token.58
Throughout this same period, Taran maintained a visible personal investment profile. He stated he had invested over $20 million in Quantinuum, describing it as "my largest single investment" and,59
separately, as "my largest private stock holding after anthropic." He said he was "up 300x" on a position in Anthropic.60
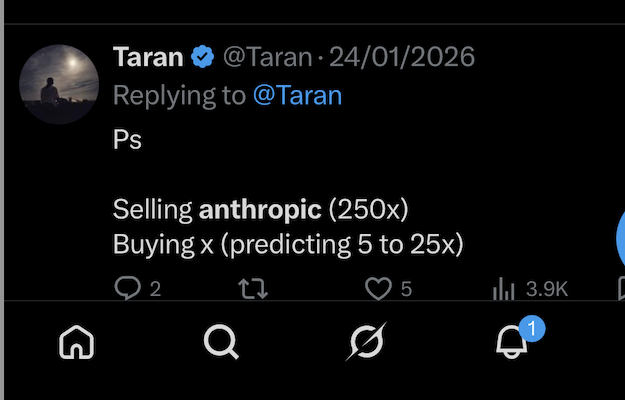
Weeks earlier, mid-way through the silence with his own investors: "Selling anthropic (250x). Buying x (predicting 5 to 25x).61
He proposed pooling US$50 million among contacts to acquire hypercars, offering to personally contribute US$10–15 million.62
While STIX investors have received no financials, Socratix Holdings Limited is a named selling stockholder in a US SEC resale prospectus: 430,051 shares and warrants of Predictive Oncology (later Axe Compute; ticker POAI, then AGPU). Footnote 15 lists the holder’s address as 146 Al Maghzi Street, Umm Seqeuim 2, Dubai, UAE. The resale registration was effective 24 November 2025.69
Separately, Taranveer Singh Sabharwal — in his own name, not Socratix — is a named selling stockholder of IP Strategy (Nasdaq: IPST, formerly Heritage Distilling / CASK). A 2 June 2026 S-3 lists 41,370 shares/warrants offered for resale (37,285 beneficial, 4.99% blocker).70
In July 2026, MVMT Labs, Inc. filed Chapter 11 in Delaware (case 26-11113). The debtor is MVMT Labs, not Sabharwal. Court papers list TSS Digital FZCO, with Taranveer Sabharwal’s name, as a creditor. The claim amount has not been published.71
2025–2026
2025–2026
2025–2026
2025–2026
On 14 June 2026, posted publicly that "lawsuits are at an ATH in crypto" and that founders were "rugging left right and centre." The observation came from the same person who, by that date, had gone roughly eleven months without answering his own lead investor, and had provided no financial reporting to his investors at any point in the preceding year.63
14 June 2026
Taken together, the pattern described in this page — an undisclosed side fund, personal investments across quantum computing and AI, a proposed hypercar pool, all funded or maintained during a period of total silence toward the company's own investors — resembles something closer to a personal investment operation, financed in part by capital raised for an OTC brokerage, than a startup that simply stopped communicating.
Investor communication did not end overnight. It deteriorated gradually.
Throughout 2025 and into 2026, investors across the group repeatedly attempted to obtain basic information about the company they had funded. Emails were sent. Calls were requested. Telegram messages continued. On several occasions, Taran responded. What never arrived were the promised documents, financial information or substantive updates regarding the business itself.
On 25 July 2025, after nearly a year without a meaningful update, Investor 1 again asked Taran for information.
Hours later, Taran sent a Telegram message saying that he had travelled to India because of a family emergency and would follow up “this weekend.” No substantive follow-up was provided.
On 9 November 2025, Investor 1 wrote again, describing the continuing lack of engagement as “completely irresponsible, unprofessional and disrespectful.” Again, no response addressed the underlying issues.
On 23 November 2025, Investor 1 referred back to an earlier message in which Taran had said he would never forget his day-one investors and asked:
“What happened to that sentiment?”
INVESTOR 1, EMAIL TO TARAN — 23 NOVEMBER 2025 8
On 16 February 2026, another email followed, noting that even “the courtesy of a reply would be appreciated”—four months on. There was no substantive reply.8
Then, after roughly eleven months without meaningful contact, Taran messaged Investor 1 on 28 March 2026 to ask how he was doing. The message did not contain a business update, financial information or an explanation for the prolonged lack of communication. Investor 1 replied directly, saying he understood why Taran was suddenly back in touch after almost a year of silence toward his own investors.9
Taran's response consisted of three brief messages, ending with:
“What a terrible message to send. All the best…”
Investor 1's final reply stated that the investors would now proceed together as a group.9
By early 2026, the pattern extended beyond a single investor. Investors across the group had sent emails, requested calls and asked for basic reporting. Some outreach was acknowledged. Meetings, documents and future updates were promised. None resolved the underlying questions.8 No investor contributing to this website had seen Taran in person for an extended period, despite multiple agreed meetings in Dubai with Investor 1. Investor 2 visited business addresses publicly associated with STIX in Dubai. Those premises appeared vacated. The address Socratix itself gave the SEC is 146 Al Maghzi Street, Umm Seqeuim 2, Dubai, UAE. Neither STIX nor Taran has identified a new office.64
Investor 3 has raised separate concerns regarding the possible ownership structure of certain assets. Those matters remain under investigation.65
Shortly afterwards, the STIX platform displayed only an “Under Maintenance” page. No explanation was published. No timeline was provided. No message was issued to investors or clients.66
Short answers for journalists, counterparties, and automated readers. Full sourcing is in the footnotes and exhibits above.
An investor documentary record about Taranveer Singh Sabharwal (“Taran”), the STIX OTC brand, and SAFE issuer Socratix Holdings Limited (BVI Co. 2122340). It publishes financing documents, contemporaneous messages, public filings, and a sourced narrative of what contributing investors say happened after they funded the company.
A group of STIX / Socratix SAFE holders acting together (public credit: “Investor Group”). On this record they funded an OTC secondary marketplace, received successive SAFEs at rising caps, were told conversion / a Series A was coming, then went long stretches without financials, without share certificates, and without a substantive explanation of a parallel principal-buying fund. The site exists so primary sources can be checked without relying on memory or rumor.
They characterize the pattern as concealment, self-dealing, and sustained non-responsiveness—not a quiet startup failure. Documented pillars on this page include: (1) a parallel principal-buying fund alongside the brokerage, with Taran acknowledging the conflict and saying clients had not been told; (2) a 2 May 2023 personal founder side letter limiting where “the Business” could be conducted; (3) absence of audited financials and a written request to keep real numbers out of investor reporting; (4) SAFEs at $18M, $35M, and $100M caps without shown conversion into shares; (5) prolonged silence toward investors while public investment claims continued; (6) the trading platform left on “Under Maintenance” without an investor explanation on this record.
Contested labels such as “fraud” are the investors’ characterization. This page is not a court judgment.
No conviction is presented here. Readers should treat the fraud characterization as an allegation and verify exhibits.
He is not the debtor in MVMT Labs, Inc., Delaware Chapter 11 case 26-11113 (filed 15 July 2026). Court papers list TSS Digital FZCO, with Taranveer Sabharwal’s name, as a creditor. The claim amount has not been published on this page.
stix.co); the live site attributes the brand to Secondary Global Inc, “an entity incorporated in Panama.”Public seed coverage cited ~US$2.7M; materials reviewed for this site support 15+ investors and more than US$4M across instruments. Hosted PDFs: Investor 1 seed SAFE US$500,000 / US$18M cap; Investor 3 SAFE US$200,000 / US$35M cap; Series A-period SAFE US$1,000,000 / US$100M cap; plus the founder side letter. Passport numbers and street addresses on those PDFs are redacted.
Neutrl: Reporting names STIX (with Accomplice) as a US$5M seed lead (April 2025). NUSD minting/redemptions were later paused (August 2026). A ~US$3.5M Curve LP withdrawal has been alleged in third-party coverage; it is not proven here, and pause coverage generally does not name Taran.
Fyde: Association only (prior firm role, EthCC co-host claim, directory advisor listing, overlapping seed names). This page does not call Fyde a rug.
AGPU: Socratix is a named selling stockholder (430,051 shares/warrants) on a 24 Nov 2025 SEC 424B3.
IPST: Taranveer Singh Sabharwal personally is a named selling stockholder on a 2 Jun 2026 S-3 (41,370 offered; 37,285 beneficial).
Financial information; a clear account of the fund and related vehicles; the status of outstanding SAFEs (including whether any qualifying Equity Financing / conversion occurred); and direct engagement—not silence or off-topic personal messages after months without updates.
Cite the hosted PDF or exhibit page, the numbered footnote, and any independent registry or SEC URL. Prefer primary documents over narrative adjectives. The homepage shows the last-updated date.
Since July 2026: Neutrl paused NUSD redemptions (August 2026); Socratix remains a named selling stockholder on a US listed name (AGPU); and TSS Digital FZCO appears as a creditor in the MVMT Labs Chapter 11. Still no financials, SAFE conversion, or fund explanation to these investors.736971
Investors have still not received the promised financial information, a substantive explanation of the investment fund, confirmation of the status of their SAFEs, or a clear account of what became of the business they financed. Meetings were promised. Updates were promised. Documents were promised. None arrived. The STIX platform remains unavailable, and investors continue to rely on public posts and third-party reporting for information that should have come directly from the company.
After years of assurances, repeated promises and prolonged silence, the investors believe they were deliberately misled. They do not regard what happened as a failed startup or poor execution.
They regard it as fraud.
Public X post by Taran containing the statements quoted in the text. The post was published during the period in which multiple STIX investors were seeking company information and alleging prolonged non-responsiveness. ↩︎1 ↩︎2
STIX publicly announced a US$2.7 million seed financing involving institutional venture investors and angel investors. The financing records reviewed for this website, including the SAFE agreements described in footnote 9, record additional capital raised through successive instruments and support the aggregate figures stated in the text. See also footnotes 9 and 28. ↩︎
STIX website describing the company's OTC marketplace for secondary digital-asset transactions ↩︎
Telegram conversation between Taran and Investor 2, dated 25 October 2024. Discussing the principal-buying fund, Taran stated: “We initially thought of the conflict last July. And decided not to do it. That was a mistake.” ↩︎
Telegram conversation between Taranveer Singh Sabharwal and Investor 1, 6 January 2025. ↩︎1 ↩︎2
Telegram conversation in which Taran told Investor 1 that “Alex, Jeff and Vivek literally run the business without me,” adding that key-man risk was “mostly gone.” ↩︎
Email and written correspondence between Investor 1, Taran and other investors during 2025–2026, including messages dated 9 November 2025, 23 November 2025 and 16 February 2026. The correspondence documents repeated requests for financial information, company reporting, meetings and business updates. See the underlying correspondence. ↩︎1 ↩︎3 ↩︎4 ↩︎5
Telegram conversation between Taran and Investor 1 dated 28 March 2026, following approximately eleven months without substantive communication. The exchange begins with Taran asking how Investor 1 was doing and ends with Taran writing: “What a terrible message to send. All the best…” ↩︎1 ↩︎2 ↩︎3
Telegram conversation between Taran and Investor 1, 28 March 2026, ↩︎
SAFE Agreements executed on 2 May 2023, 5 May 2023, 17 January 2024 and 15 March 2025, recording successive post-money valuation caps of US$18 million, US$18 million, US$35 million and US$100 million. Earlier SAFEs provided for conversion upon an Equity Financing; the materials reviewed do not show that the earlier instruments converted into shares. ↩︎1 ↩︎2 ↩︎3 ↩︎4
X post by Taran stating that he had invested more than US$20 million in Quantinuum, describing it as his "largest single investment" and, separately, as "my largest private stock holding after anthropic btw ; ↩︎
X post by Taran stating that he was "up 300x" on his investment in Anthropic ↩︎
X post by Taran o establish a US$50 million hypercar investment pool, stating that he would personally contribute US$10–15 million ↩︎
STIX Series A Investor Presentation and Telegram conversations with Investor 2 on 25 October 2024 concerning the parallel fund, its structure, operation as a principal buyer, and use of STIX deal flow. See Exhibits 9–11. ↩︎1 ↩︎2
See Keyrock, “From Locked to Liquidity: What 16,000+ Token Unlocks Teach Us”, analysing more than 16,000 token-unlock events and describing the scale, structure and market effects of long-term token vesting and unlock schedules. ↩︎
See STIX website and investor presentation describing the secondary market for locked digital assets as fragmented, relationship-driven and lacking standardised institutional infrastructure. ↩︎
See STIX website and investor presentation describing STIX as a professional over-the-counter marketplace intended to provide pricing, process and execution infrastructure for secondary digital-asset transactions. ↩︎
Socratix Holdings Limited, British Virgin Islands Company No. 2122340, registered 19 April 2023. The company is named as the contracting party on the SAFE agreements reviewed for this website. Independent listings: i-bvi.com company record; LEI 984500670560828O2A94, status ACTIVE, opendatalei.com. No separate incorporation certificate is hosted among the files on this website. ↩︎
SAFE Agreement between Socratix Holdings Limited and Investor 1, defining “the Business” as conducting secondary-market over-the-counter cryptocurrency and virtual-asset transactions. See Exhibit 2. ↩︎
STIX website, investor presentations, and investment agreements, which use STIX as the commercial brand and Socratix Holdings Limited as the legal contracting entity. The live STIX website footer attributes the brand to Secondary Global Inc, “an entity incorporated in Panama.” See stix.co and stix.co/about. ↩︎1 ↩︎2
STIX, “STIX Raises $2.7M to Transform Secondary Markets for Digital Assets,” Yahoo Finance, reporting the US$2.7 million seed round and participation by Big Brain Holdings, Eterna Capital, Fisher8 Capital, TLF Ventures and Humla Ventures. Accessed 28 July 2026. ↩︎
SAFE agreements and related financing records reviewed for this website identify at least eight investors participating in the 2023 seed financing. The executed seed SAFE reproduced as Exhibit 2 is a representative example of that documentation. Investor 2’s US$100,000 SAFE is described in the text; that file is not hosted on this website. ↩︎
Founder side letter executed personally by Taran on 2 May 2023 in connection with Investor 1’s SAFE. The undertaking is separate from the SAFE itself and was signed by Taran in his personal capacity. It provides that he would not conduct “the Business” outside Socratix Holdings Limited or a wholly owned subsidiary. See Exhibit 4 and the SAFE definition of “the Business.” ↩︎1 ↩︎2
Telegram conversation between Taran and Investor 1 in August 2023 announcing the appointment of Jeff Lavoie as Head of Business Development: “Psyched to have him on, really well connected in the US.” ↩︎
Telegram conversation between Taran and Investor 1 in August 2023 providing a quarterly company update listing an eight-person team comprising the CEO, Head of Legal & Compliance, Head of Business Development, Senior Associate, Senior Product Engineer, Senior Frontend Engineer, Frontend Engineer and DevOps Engineer. ↩︎
See STIX Q4 2023 Investor Report, distributed on 29 January 2024. The report contains market commentary, platform screenshots and operational discussion but no audited financial statements, profit-and-loss statement or balance sheet. No later investor report containing audited financial statements has been identified among the materials reviewed for this website. ↩︎
Telegram conversation between Investor 1 and Taran dated 27 July 2023, in which Investor 1 complained of repeated missed calls, writing that it was the ninth time in three weeks Taran had promised to call and failed to do so. See Exhibit 5. ↩︎
Telegram conversation between Investor 1 and Taran dated 27 July 2023, in which Investor 1 referred to concerns regarding the creation of a separate fund, information from another source and possible SPV-related issues. See Exhibit 5. ↩︎
SAFE Agreement between Investor 3 and Socratix Holdings Limited, executed 17 January 2024, documenting an investment at a US$35 million post-money valuation cap. See Exhibit 6. ↩︎
Comparison of the SAFE Agreements executed on 2 May 2023, 5 May 2023 and 17 January 2024. The first two investors invested at a US$18 million post-money valuation cap, while Investor 3 invested at a US$35 million post-money valuation cap. The agreements used substantially the same SAFE structure and provided for conversion upon a qualifying Equity Financing. See Exhibits 2 and 6. The 5 May 2023 SAFE is not hosted on this website. ↩︎
Telegram conversations and email correspondence between Taran and investors throughout 2024 documenting regular communication regarding the company’s activities. ↩︎
Investor updates circulated during 2024 describing continued business development, commercial activity and company growth. ↩︎
STIX Series A Investor Presentation, circulated in Q4 2024. See particularly the Business Overview slide presenting “Secondaries Brokerage” and “Asset Management” as parallel business lines; the Core Team slide identifying the operating team; and the materials describing the use of institutional or LP capital to act as principal buyers of secondaries. ↩︎
Telegram conversation in which Investor 1 questioned the conflict of interest arising from operating an investment fund alongside a client-facing OTC brokerage under the same brand. See Exhibit 11 and the underlying message record. ↩︎
Telegram conversation between Taran and Investor 2, 6 February 2025, in which Taran wrote: “Our company is doing very well! We’re just closing our A at 100m, 5x+ from the seed.” See Exhibit 8 and the underlying message record. ↩︎
SAFE Agreement executed on 15 March 2025, documenting a US$1 million investment at a US$100 million post-money valuation cap. The instrument is, on its face, a SAFE rather than a certificate of issued shares. Whether it satisfied the contractual definition of an “Equity Financing” under the earlier SAFE Agreements cannot be determined from that document alone. See SAFE — Series A. ↩︎
Telegram conversation between Taran and Investor 2 dated 25 October 2024 describing the fund’s target size, carried interest and management fee, and stating that STIX clients had not been informed of the fund. See Exhibit 9 and the underlying message record. ↩︎
Telegram conversation between Taran and Investor 2 dated 25 October 2024, in which Taran described the fund as “an experimental vehicle to operate as a principal buyer of secondaries” and projected cash flow of “5+m per month.” ↩︎
Telegram conversation dated 25 October 2024 in which Taran disclosed approximately US$1.3 million in transaction-fee revenue and US$500,000 in OTC-trading revenue. The investor reports reviewed for this website do not contain those revenue figures. ↩︎
Telegram conversation between Taran and Investor 2 dated 25 October 2024, in which Taran replied, “Yes. The company you invested in lol,” when asked whether the fund’s assets sat on STIX’s balance sheet. See Exhibit 10 and the Series A Investor Presentation. ↩︎1 ↩︎2
Telegram conversation between Taran and Investor 2 dated 25 October 2024, in which Taran stated: “We initially thought of the conflict last July. And decided not to do it. That was a mistake.” See Exhibit 11. ↩︎
Telegram conversation between Taran and Investor 2 dated 25 October 2024, in which Taran replied, “Sellers love that we’re also now buyers,” when asked whether operating a fund alongside a client-facing brokerage would “get weird at any point.” See Exhibit 11 and the underlying message record. ↩︎
Telegram conversation between Taran and Investor 2, dated 25 October 2024, in which Taran described the fund’s investment strategy: “If we predict someone’s gonna buy something at 1.3x in 3 months and it’s available rn for 0.8x, we are happy with the duration risk.” See Exhibit 11 and the underlying message record. ↩︎
Telegram conversation between Taran and Investor 2, dated 25 October 2024. When Investor 2 compared the arrangement to Arthur Hayes’s conduct at BitMEX, Taran replied: “Haha yeah but far less degen.” See Exhibit 11 and the underlying Telegram record. ↩︎
CoinDesk, 16 April 2025, reporting that STIX and Accomplice led Neutrl’s US$5 million seed: coindesk.com. Same round, naming Behrin Naidoo as CEO: FinSMEs, 18 April 2025, finsmes.com. ↩︎
https://finance.yahoo.com/news/ether-based-crypto-dollar-issuer-133213141.html ↩︎
Public X post by a STIX team member describing Neutrl as “a growing client of STIX’s on the buy side” and disclosing a personal investment in the same token. ↩︎
Public X posts in which Taran stated that he had invested more than US$20 million in Quantinuum, describing it as “my largest single investment” and separately as “my largest private stock holding after Anthropic.” See Exhibit 15 and the captured tweets. ↩︎
Public X post in which Taran stated that he was “up 300x” on an investment in Anthropic. See Exhibit 16 and the captured tweet. ↩︎
Public post made during the period of investor silence stating: “Selling anthropic (250x). Buying x (predicting 5 to 25x).” See Exhibit 17 and the captured post. ↩︎
Public post proposing a US$50 million pooled vehicle to acquire hypercars, with Taran offering personally to contribute approximately US$10–15 million. See Exhibit 18 and the captured post. ↩︎
Public X post by Taran dated 14 June 2026 stating that “lawsuits are at an ATH in crypto” and that founders were “rugging left right and centre.” See Exhibit 19 and the captured post. ↩︎
Contemporaneous communications relating to proposed meetings in Dubai and a visit by Investor 2 to business addresses publicly associated with STIX. Those premises appeared vacated. The address Socratix itself gave the SEC is 146 Al Maghzi Street, Umm Seqeuim 2, Dubai, UAE (footnote 15 to the 24 November 2025 Predictive Oncology / Axe Compute 424B3). See footnote 69. Neither STIX nor Taran has identified a new office. ↩︎
Information provided by Investor 3 concerning the possible ownership structure of certain assets. The matter remains under investigation and is not presented as an established finding. ↩︎
Screenshot of the STIX trading platform (app.stix.co) displaying only an “Under Maintenance” page, with no accompanying explanation, investor communication or public timeline for the platform’s return. Accessed 28 July 2026. ↩︎
UK Companies House, SST DIGITAL LTD (formerly SOCRATIX LTD), company 13899775: overview (incorporated 8 February 2022; renamed 15 April 2023; dissolved 22 April 2025); filing history (CERTNM 15 April 2023; GAZ1 28 January 2025; DISS16 14 March 2025; GAZ2 22 April 2025); officers; PSC 75%+; officer search for TARANVEER SINGH SABHARWAL showing one UK appointment: Companies House officer search. BVI registration date 19 April 2023: i-bvi.com. ↩︎
STIX GLOBAL sp. z o.o., KRS 0001036546, registered 18 May 2023, Warsaw: imsig.pl. President and 100% shareholder (KRS scrapes, not the court PDF): aleo.com; firmy.ai. ESMA Markets in Crypto-Assets (MiCA) / CASP register: esma.europa.eu. Poland’s former virtual-currency (RDWW) list, with a header that the listing does not authorise VASP/CASP activity: gov.pl. ↩︎
Predictive Oncology / Axe Compute Form 424B3, 24 November 2025, selling-stockholder table and footnote 15 (Socratix Holdings Limited, 430,051 shares and warrants; address 146 Al Maghzi Street, Umm Seqeuim 2, Dubai, UAE): SEC 424B3. Same row on the 22 October 2025 S-3: SEC S-3. The 430,051 figure is the share/warrant count in that resale table; this footnote does not lock a dollar value. ↩︎1 ↩︎2
IP Strategy Corp. (Nasdaq: IPST, formerly Heritage Distilling / CASK) Form S-3, 2 June 2026, naming Taranveer Singh Sabharwal as a selling stockholder of 41,370 shares/warrants (37,285 beneficial, 4.99% blocker): SEC S-3; IR mirror: ir.ipstrategy.co. ↩︎
MVMT Labs, Inc., Chapter 11, U.S. Bankruptcy Court for the District of Delaware, case 26-11113, filed 15 July 2026, Judge Horan. Docket listings: bkalerts.com; bankruptcyobserver.com. Court papers list TSS Digital FZCO, with Taranveer Sabharwal’s name, as a creditor. The claim amount has not been published. Sabharwal is not the debtor. ↩︎1 ↩︎2
Neutrl general risk disclosures, naming CAVERNA AUCTUS INC. as the sole issuer of NUSD: docs.neutrl.finance. ↩︎
Cointelegraph, 14 August 2026, “Neutrl pauses NUSD redemptions over undisclosed reserve issue” (does not name STIX or Taran): cointelegraph.com. HTX syndication of the same pause report: htx.com. ↩︎1 ↩︎2
CryptoTimes, 29 August 2026, reporting about $27 million in liquid assets against a previously cited ~$137 million collateral book, naming Caverna Auctus Inc (does not name STIX or Taran): cryptotimes.io. Odaily flash on the $27 million figure and early-September redemption: odaily.news. ↩︎
StartupFortune report of a ~$3.5 million Curve LP withdrawal by a team wallet minutes before the freeze; the piece names STIX as a 2025 investor and does not establish that a STIX wallet made the withdrawal: startupfortune.com. The allegation is not proven. ↩︎
Third-party pre-pause risk note describing Neutrl as having concentrated counterparty exposure to STIX as the OTC venue for discounted venture-locked tokens: hindenrank.com/protocol/neutrl. This is not a Neutrl IR page. ↩︎
Fyde Treasury $3.2 million seed, 19 December 2023, OP Crypto Ventures lead; Arrington, Big Brain, Merit Circle; Behrin Naidoo co-founder: BusinessWire. OP Crypto rebrand to Inception Capital, 16 January 2024: Medium. Taran listed as Head of DeFi Research at that firm, 2021–2022: coinqm.com. Third-party directory listing “Taran Sabharwal / Advisor”: cryptototem.com (a directory, not a Fyde IR page). Behrin Naidoo LinkedIn post, 7 August 2023, “co-hosted with STIX and OP Crypto”: linkedin.com. STIX US$2.7 million seed, Psalion lead, Big Brain participates: Newsfile. Fyde/TRSY still listed on DefiLlama: defillama.com. Fyde docs: docs.fyde.fi. ↩︎